Argentina’s 211.4% Inflation: Why Digital Dollars Still Need Gatekeepers
Argentina’s 2023 inflation crisis gave dollar stablecoins a practical role in saving and spending. The evidence connects paychecks, payment apps and contract reform, while exposing the limits of calling USDT money beyond anyone’s control.
Key Points
- Argentina’s consumer prices rose 211.4% during 2023, intensifying the challenge of preserving purchasing power.
- A 2023 industry interview described people converting paychecks into USDT or USDC; that was an observation, not a census of every worker.
- Contract currency reform and digital transfers did not turn USDT into legal tender or remove issuer controls.
Chronological Timeline
Chainalysis publishes the Lemon Cash interview describing conversion to USDT or USDC.
The decree changes rules for performance in the agreed currency.
The decree is published; contractual freedom remains subject to legal limits.
INDEC records annual inflation of 211.4% and monthly inflation of 25.5%.
1. A year measured in disappearing purchasing power
Argentina’s official statistics agency INDEC recorded a 211.4% rise in consumer prices across 2023. December alone added 25.5% compared with November. These are different measures: an annual increase and a monthly increase, not a claim that every shop changed every price at the same pace.[4]
The national index describes a basket of consumption, not one household’s bank balance. A salary’s actual purchasing power also depends on pay changes and what the household buys. The headline figure captures a national crisis while leaving room for different experiences across families.[4]
That distinction makes the story more human, not less urgent. A balance can remain numerically unchanged while the goods it can buy recede. Digital dollars entered this gap between money held and spending postponed; their appeal must be assessed against the costs and risks of reaching them.[4][1]
2. The paycheck, rather than the secret doorway
In its October 11, 2023 report, Chainalysis interviewed Alfonso Martel Seward, Lemon Cash’s head of compliance and AML. He described people moving paychecks into USDT or USDC, linking demand to inflation and foreign-currency restrictions. This is an identified industry participant’s account, not a population-wide measurement.[1]
A paycheck is a useful starting point because it connects earning with the interval before spending. The interview does not measure how much of each salary was converted or prescribe a fixed day and hour. It supports a reported behavior, rather than a uniform national routine.[1]
The crucial question is not whether a transaction looks modern. It is what the saver ends up holding. A token balance and a physical dollar note are different arrangements, even if both are discussed in dollars. The route into the asset is only the beginning of the story.[2]
3. The dollar comes back to the checkout
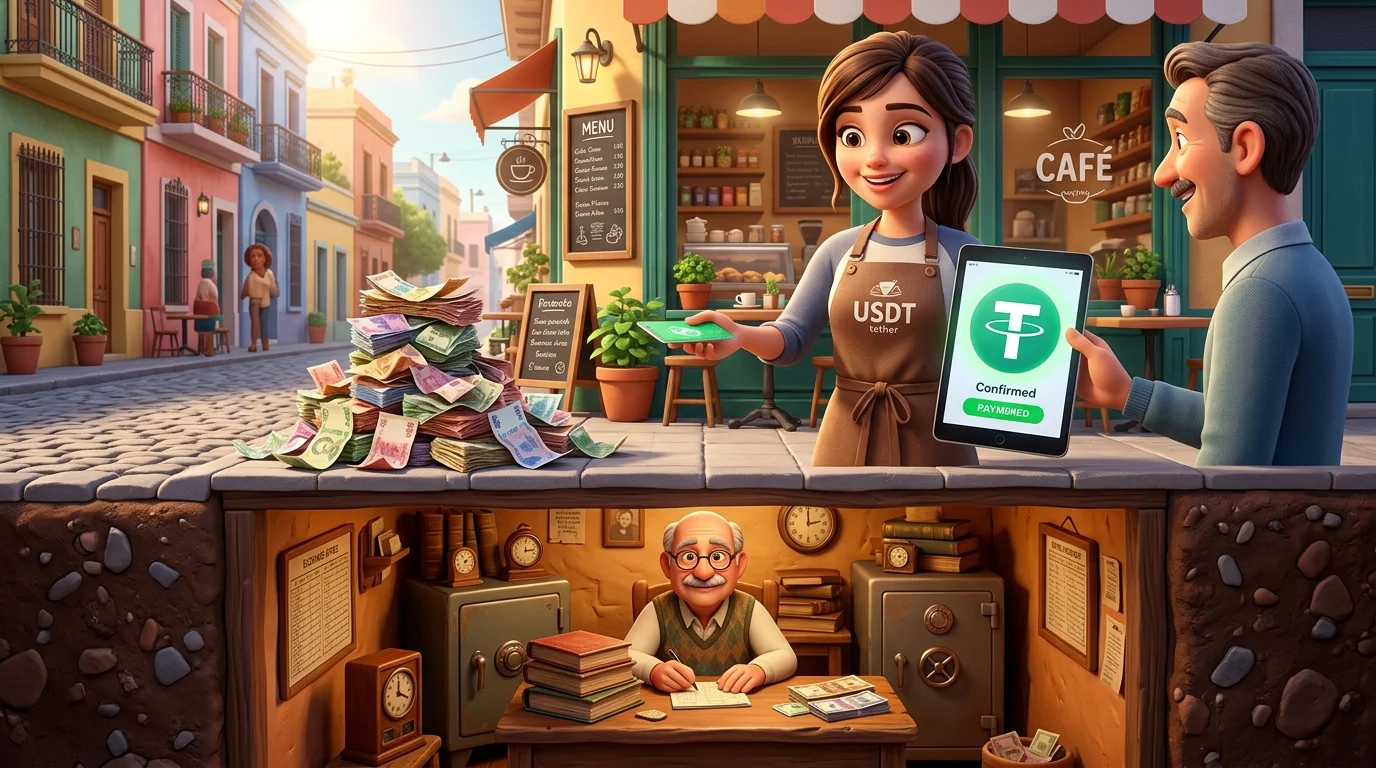
The same report described Lemon Cash’s debit card selling a user’s crypto when the card was used, with the merchant receiving local currency. That separates the asset held before purchase from the money received by the shop. It is not evidence that every merchant accepted USDT directly.[1]
A checkout therefore need not become a blockchain terminal for crypto to play a role upstream. This is the story’s practical hinge: saving and spending can use different units and different services. Calling the whole process a single peer-to-peer transfer hides the conversion step that makes the purchase possible.[1]
The arrangement also makes the intermediary visible again. A usable balance is more than a number on a screen: there must be a way to convert it and complete the payment. The experience cannot be inferred from a token’s name, and one product example cannot establish identical fees or settlement times across competing apps.[1]
4. What Milei’s decree actually changed
DNU 70/2023 was signed on December 20, 2023 and published the following day. Articles 250 and 251 replaced Civil and Commercial Code provisions on delivering the agreed currency, including currency without domestic legal-tender status. Article 252 retained limits based on law and public order for contractual freedom.[3]
That is a change to contractual obligations, not a declaration that USDT became national legal tender. The cited provisions do not name Bitcoin or USDT. They cannot by themselves prove that every crypto arrangement was newly authorized, that prior use was wholly illegal, or that every merchant had to accept tokens.[3]
A contract and a payment rail answer different questions. The first sets the obligation between parties; the second carries out a transfer. Neither an app’s convenience nor the existence of a currency clause proves that the other layer has disappeared. Treating reform as a blanket technological endorsement would erase this distinction.[3]
5. A different dollar, with different gatekeepers
Tether’s terms, updated February 26, 2026 and checked for this story, reserve powers to freeze tokens and suspend services. Direct redemption requires verified-customer status and is subject to conditions and fees. The terms also state that the tokens are not government-backed legal tender or insured deposits. These are current terms, not a reconstruction of every 2023 condition.[2]
The interpretation is therefore a trade-off, rather than liberation from every authority. Moving away from peso exposure can introduce reliance on an issuer, a platform and a usable conversion route. A dollar reference does not guarantee constant purchasing power or make every token holder equivalent to a bank depositor.[2]
Argentina’s episode illustrates a sharper paradox than a triumphant dollar empire: a new transfer medium can carry an old monetary preference. Blockchain can change how value moves without removing the institutions that make it spendable. That is the enduring question behind the paycheck: who must still perform when the holder wants to use the money?[1][2]
Key Takeaways for Investors & Builders
Separate the asset from the payment
A crypto-funded card can still pay the merchant in local currency.
Measure the risk that was exchanged
Leaving peso exposure does not eliminate issuer and conversion risks.
Contract choice is not legal tender
An agreement between parties is different from a universal obligation to accept a token.
Continue reading
Explore the topic through other cases and contexts.
Sources & References
- [1]Source 1: Chainalysis: Argentina’s crypto use and the Lemon Cash interviewChainalysis · 2023-10-11
- [2]Source 2: Tether: token terms, redemption and freezing powersTether
- [3]Source 3: Argentina: original DNU 70/2023, articles 250–252Poder Ejecutivo Nacional · 2023-12-21
- [4]Source 4: INDEC: December 2023 consumer price reportINDEC · 2024-01-11