Black Thursday: How Zero-DAI Auctions Exposed MakerDAO’s Liquidation Design
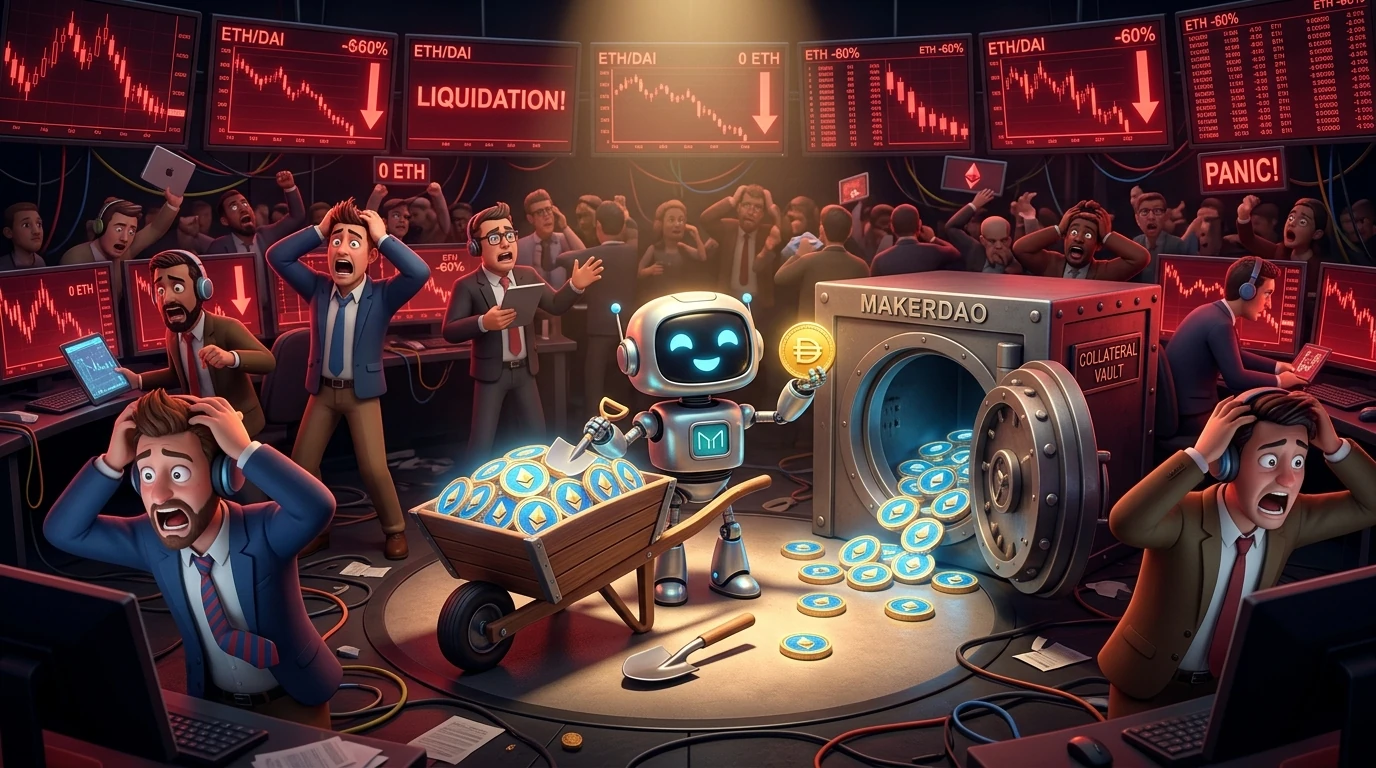
On March 12, 2020, falling ETH prices, Ethereum congestion, delayed oracle updates, scarce DAI liquidity and weak keeper competition met inside MakerDAO’s liquidation system. For roughly two to three hours, some collateral auctions returned 0 DAI, leaving protocol debt and Vault owners with losses that governance later had to separate and assess.
Key Points
- On March 12, 2020, an ETH price crash and severe Ethereum traffic pushed many Vaults below their liquidation ratios while oracle updates and auction transactions struggled with high gas prices.
- Maker’s response thread reported that one keeper continued liquidating and bidding zero without competition for about two to three hours; the record does not establish theft or criminal intent.
- The incident left roughly $4 million of protocol bad debt at the time. Maker’s debt-auction design minted and sold new MKR for DAI, increasing token supply rather than selling corporate shares.
Chronological Timeline
The market decline makes undercollateralized Vaults eligible for liquidation while Ethereum traffic and gas prices rise sharply.
The response thread cites slippage risk, slow confirmation and insufficient liquidity as reasons keepers stopped or could not absorb the wave of auctions.
One keeper continues triggering liquidations and bidding zero without competing bids until other keepers return.
Governance records describe oracle-update failures, bidding trouble and scarce DAI; Flop debt auctions recapitalize most protocol losses.
A formal poll separates protocol debt from Vault-owner losses and estimates the latter at less than 4 million DAI beyond an optimal liquidation outcome.
A market crash reached an auction system
Maker Vaults let users generate Dai against collateral. When a Vault falls below its liquidation ratio, the protocol takes collateral and sells it in an internal auction; Dai raised by that sale pays the outstanding obligation and liquidation penalty, and any remaining collateral can return to the owner.[3]
On March 12, 2020, ETH’s rapid decline pushed many Vaults below that threshold at once. Ethereum was congested, transaction costs rose, and liquidations arrived faster than the available market participants and liquidity could comfortably absorb them.[1][2]
The later governance review did not reduce the event to one broken bot. It recorded periods when the Maker price oracle failed to update because of unexpectedly high gas, while keepers also struggled with transaction fees and a shortage of DAI for bids.[2]
Those failures interacted: delayed prices changed when Vaults became eligible, congestion obstructed transactions, and scarce bidding capital weakened price discovery just as collateral values were falling.[1][2]
Zero was a valid bid until competition arrived
Keepers were independent market participants, often automated, that monitored liquidations and bid Dai for collateral. The protocol supplied auction contracts and open-source software, but it did not guarantee that enough operators, working nodes or liquid Dai would appear for every auction.[3][4]
Maker’s real-time response thread reported that only one keeper continued triggering liquidations and bidding zero without competition for roughly two to three hours. A ten-minute bid timeout allowed the largest standing bid to close if nobody topped it, so a zero bid could settle during that absence of competition.[1]
The primary record establishes zero-return auctions and a temporary concentration of participation. It does not establish criminal intent or a verified market-value total for all collateral settled through those auctions.[1][2]
The operational lesson was also narrower. A smart contract can execute exactly as configured while its economic result deteriorates because congestion, timing, external software and market liquidity determine whether competitive bids reach it.[1][3][4]
Collateral value, system debt and user loss were different numbers
When an auction returns too little Dai, the Vault’s obligation is not fully erased and the shortfall becomes protocol debt. On March 12, the response thread described a surplus that had moved from roughly positive $500,000 to negative $4 million and separately summarized about $4 million of bad debt in the system.[1]
Maker’s designed backstop was a debt auction, also called a Flop auction. The system mints new MKR and sells it to bidders for Dai; the Dai covers the deficit while the increase in MKR supply dilutes existing token holders. The protocol record describes the issuance and sale of a governance token to cover debt, rather than a corporate share sale.[1][3]
Vault-owner loss required another calculation. The April 6 poll noted that liquidation can consume all collateral even in normal conditions, then estimated the additional loss caused by suboptimal operation at less than 4 million DAI. That estimate was not the market value of every zero-bid lot and was not the same as protocol bad debt.[2]
Governance therefore debated compensation as a separate policy question. The official poll presented arguments on both sides and described further analysis and another vote as prerequisites, rather than treating a rough estimate as an automatic debt owed to every affected user.[2]
Black Thursday changed what resilience meant
The event showed that collateralization alone did not make Dai self-correcting. Solvency also depended on price feeds arriving, Ethereum transactions landing before auction timers expired, keepers staying online and bidders having enough Dai.[1][2][3]
During the emergency discussion, participants considered changing lot sizes, extending bid time, raising the initial bid and improving access to debt auctions. The range of proposals reflected several linked bottlenecks rather than a single malicious cause.[1]
Debt auctions transferred the protocol deficit through newly issued MKR, while the compensation process addressed possible residual losses to Vault owners. Keeping those channels separate explains who bore which cost and avoids calling every figure a loss of collateral.[1][2][3]
Black Thursday remains a case study in market infrastructure: code, incentives and external operators form one system. When network capacity and liquidity disappear together, a formally open auction can cease to produce a competitive price.[1][2][4]
Key Takeaways for Investors & Builders
On-chain auctions still depend on transactions arriving
Open contracts cannot create competition when oracle updates, nodes or keeper bids fail to reach the chain before the timer closes.
Collateral sold, protocol debt and owner loss are separate measures
The incident’s roughly $4 million protocol deficit and the later estimate of under 4 million DAI in additional Vault-owner losses described different burdens.
The backstop diluted a governance token
Debt auctions minted the governance token MKR and exchanged it for Dai to recapitalize the system, increasing the token supply. The protocol record describes a token debt auction rather than a corporate share sale.
Continue reading
Explore the topic through other cases and contexts.
Sources & References
- [1]Source 1: Black Thursday response threadMaker Governance Forum · 2020-03-12Accessed 2026-09-05
- [2]Source 2: Vault Compensation PollMaker Governance · 2020-04-06Accessed 2026-09-05
- [3]Source 3: Multi-Collateral Dai white paperMakerDAO · 2020-02-17Accessed 2026-09-05
- [4]Source 4: Official Auction Keeper repositorySky EcosystemAccessed 2026-09-05